The platform that allows more people, to invest in more of what matters.

An FMA-licensed trading marketplace for real-world assets — built for everyday Kiwis to discover, invest in, trade and manage ownership interests.

What would you like to invest in?

Tressel's regulated digital infrastructure lets you discover, invest in, trade and manage interests in real-world assets. One platform, a growing range of asset classes — starting with residential property.

See all asset classes
Residential Property is live through Housies. Tap an asset class to learn more.
LiveResidential Property

Why Tressel

For generations, investing in real-world assets has belonged to the few.

Not because opportunity was scarce. Because access was.

But the world is rapidly changing.

Technology has transformed how we communicate, travel, shop and work. Yet the way we invest in real-world assets has barely changed at all.

We think that's old fashioned & wrong. So we built Tressel.

The Tressel platform is a trading marketplace for real-world assets, designed for everyday Kiwis to discover, invest in, trade and manage ownership interests.

01One unique platform.
02Access to multiple asset classes.
03Unlimited potential applications.

One platform. Many markets.

Asset classes in development.

Residential property is first. Each new class runs on the same licensed, market-tested platform.

Residential Property

Housies is ready to go to market.

Market ready

Fine Art

Paintings, sculptures, drawings, engravings, photographs.

In development

Green Energy

Storage and generation.

In development

Natural Resources

Forestry, farming, aquaculture.

In development

Collectibles

Vintage, classic and prestige cars. Racehorses. Fine wine and rare whiskies.

In development

Commercial Property

Office buildings, commercial warehousing.

In development

The Tressel platform

Built once. Ready for every asset class.

A trading marketplace for real-world assets, backed by an automated, scalable, market-tested share registry with instant transactions. Features will continue to be enhanced as the business grows.

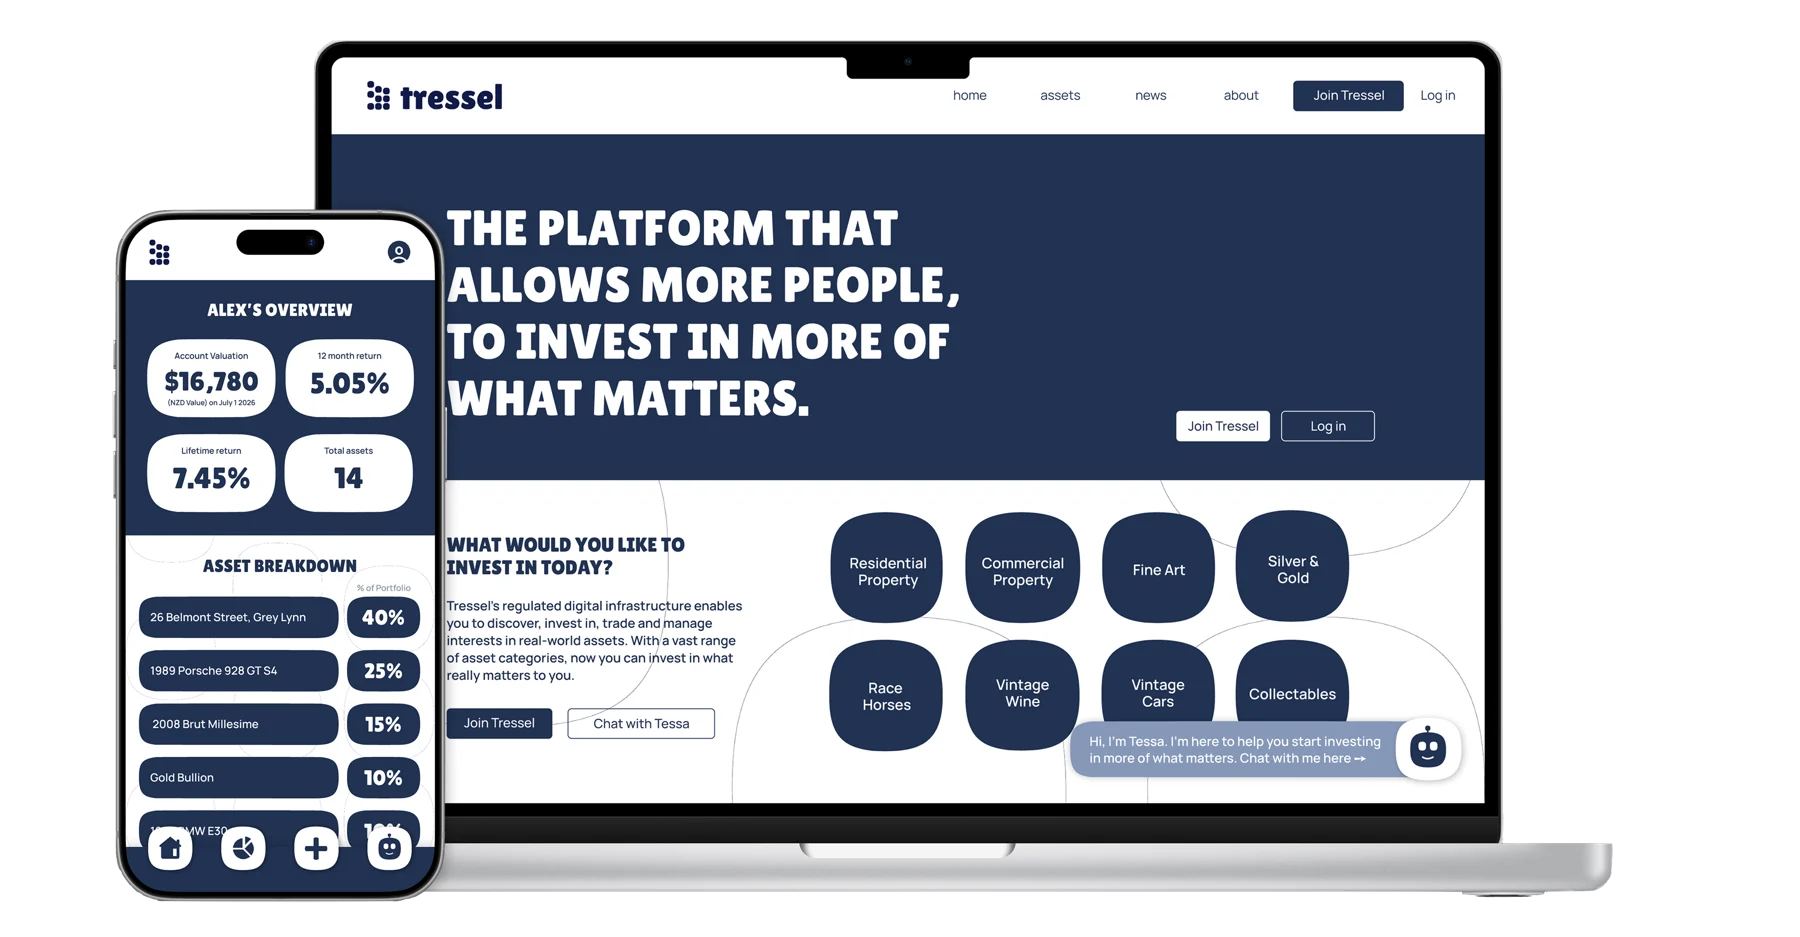
The Tressel platform on laptop and mobile, showing an investor overview and asset breakdown
Mobile native app in development
Ongoing CRM improvements & compliance
Trading secondary market ready
Customer engagement automation
Auto-invest and investor portfolio features
Dividend and refund automation
Instant settlement on completed transactions
Open banking feature enhancements

Tressel's journey so far

Licensed, tested and ready.

Tressel incorporated

Work begins on the business structure and detailed operating platform design, with asset class capability built into the CRM.

Market discovery test

High engagement from all ethnicities and age groups across the country — and proof of the model's flexibility.

FMA application lodged

Application to the Financial Markets Authority for a Market Services crowdfunding licence.

FMA licence issued

Market Services crowdfunding licence issued to Tressel on 18 June 2025.

Full market test

Housies goes live on the platform, validating the technology, compliance, market mechanics and operations.

Government engagement

Briefings with the Minister of Housing, Minister of Commerce, and Labour and ACT spokespeople.

Governance

The people behind Tressel.

Directors are appointed by resolution of a majority of shareholders under the Tressel Constitution. The Board meets monthly to review performance and strategy, and its composition is regularly reviewed to keep the right mix of skills and experience.

James Jordan

James Jordan

Founder & CEO

Extensive senior operational and strategic management experience across the public, private and non-profit sectors — most recently managing business assets of just over $250m with 150 employees, and completing a $100m apartment development.
Simon Whyte

Simon Whyte

Founder & Chairman

An accomplished director with expertise in maximising shareholder returns across diverse sectors including energy, infrastructure and tourism.

Keyur Patel

Keyur Patel

CFO

A Chartered Accountant with a long-standing interest in housing. Keyur held finance roles at Tāmaki Regeneration Company, a Crown-owned community housing provider, and has started and run two businesses.

Asset class one

HOUSIES

Making property ownership accessible to all Kiwis

The problem

Let's look at residential property.

  1. In New Zealand's major cities and towns, it's almost impossible for two young working professionals to buy their own home without parental support.
  2. It's almost impossible to invest in housing as an asset class unless you can afford to buy the whole property.
  3. We think that's old fashioned, and wrong. So we built Tressel.

Asset class one · Residential property

A better way to own a home.

01

Market ready

  • FMA licensed
  • Investment & trading platform
  • Approved secondary trading market
  • Proven operating model through Housies
02

A better way to participate

  • Enables a new generation to participate in housing
  • Introduces a co-ownership investment model
  • Unlocks liquidity & flexibility for homeowners and investors
  • Enables foreign investment capital
03

Scalable platform economics

  • Built on a repeatable compliance & transaction platform
  • Generates recurring revenue as participation grows
  • Designed to scale across multiple properties
04

Impact with returns

  • Measurable social impact alongside financial outcomes
  • Independently assessed by ImpactLab after the first 12 months of operations
  • Aligns investor returns with improved housing accessibility

Our purpose and values

Democratising home ownership.

EmpowermentEquityCollective GoodFuture Focus
We believe everyone should have the opportunity to participate in property ownership — regardless of income, background, or circumstance. By creating a new, inclusive system of ownership, we unlock access, equity and long-term wealth for individuals and society alike.

Strategic market position

Right where the housing gap is widest.

Tressel sits in the housing continuum between assisted and market ownership — positioned to help solve the housing affordability problem.

Target addressable market$10.7bn14% of NZ property transactions

Size of the market opportunity

1.2m1Projected population growth over the next 30 years
83–85k2Houses sold nationally in 2025
$1.7tn3Current total value of housing stock
35k1New homes needed each year to keep pace with population growth
108k4Property listings in 2025
1.92m4Property searches in Nov 2025 on realestate.co.nz

1. Stats NZ, internal Tressel analysis · 2. REINZ NZ Property Report Jan–Nov 2025 · 3. Reserve Bank of New Zealand · 4. realestate.co.nz

How Housies works

One home. Many investors. One Guardian.

Worked example: an $800,000 property with a 2% minimum deposit.

1

Property Co.

A Property Co. is set up to assess, buy and manage the home. Once the agreement is signed, it raises investment over 60–90 days. If the full amount isn't secured, all funds are refunded.

$800,000Property value raised
2

Property Guardian

The Guardian — the person who lives there — applies, and if accepted invests as much as they can afford, no less than 2% of the offer price.

$16,000Minimum Guardian deposit (2%)
3

Occupation Licence

The Guardian signs an Occupation Licence at 4% p.a. on the share value they don't own ($784,000). It is not a tenancy. They can buy more shares on the secondary market over time.

$603 / week$31,360 per annum
4

Property Investors

Investors receive quarterly property dividends plus anticipated capital growth, and can sell their shares on the Tressel secondary market.

~8.8% p.a.~3.2% dividend + ~5.6% growth, gross*

*Returns are projected and not guaranteed. Capital growth is based on the 30-year historical average from the Reserve Bank of New Zealand M10 housing data (March 1996 to March 2026 quarters).

Ready to buy a piece of a house?

Go to housies.co.nz

For investors

Invest in Tressel itself.

Information on Tressel's current capital raise, our roadmap and how to get in touch with the founders.